
Share this news !
July 29, 2024
The Transition 5.0 Plan includes resources of 6.3 billion euros, which are added to the 6.4 billion already provided for in the budget law, for a total of about 13 billion in the 2024-2025 biennium.
Transition 5.0 incentives in the form of Tax Credit up to 45% for reducing energy consumption
The Industry 5.0 plan introduces a new tax credit for investments made in the 2024-2025 biennium in digitization and green transition.
The incentive, and this is the most significant change from the previous Industry 4.0 plan, will be differentiated in relation to the assumed energy savings and equal to :

Savings related to Transition 5.0 Incentives must therefore be calculated at different rates depending on whether we refer to the "production structure" or just the "process affected" by the investment.
Eligible Investments
Investment in new tangible and intangible assets, including those aimed at the self-production of energy from renewable sources for self-consumption, instrumental to business operations and which are interconnected to the company's production management system or supply network are eligible for aid provided that, through the same, the innovation projects achieve an overall reduction in energy consumption of the production structure located in the national territory of not less than 3 percent or, alternatively, a reduction in energy consumption of the processes involved in the investment of not less than 5 percent.
They are eligible for the incentive as "towed" assets:
- the power generation groups
- Transformers placed upstream of electricity grid connection points, as well as electricity meters functional for electricity generation
- plants for the production of thermal energy , used exclusively as process heat and not transferable to third parties, with electrification of thermal consumption, supplied by self-consumed renewable electricity or certified as renewable through a renewable energy supply contract
- auxiliary plant services
- The facilities for storing the energy produced
Access to Facilities and Timelines
Incentives are recognized only if energy savings are certified by an independent evaluator and following submission of the project by an accredited company and acceptance of the same by the GSE.
The Energy Service Company (ESCo) that certifies the savings and submits the project must be certified by an accredited body according to UNI CEI 11352.
The tax credit can be used exclusively by offsetting, via the F24 form submitted through the online services of the Internal Revenue Service no later than Dec. 31, 2025.
Certification of savings and paperwork with the GSE
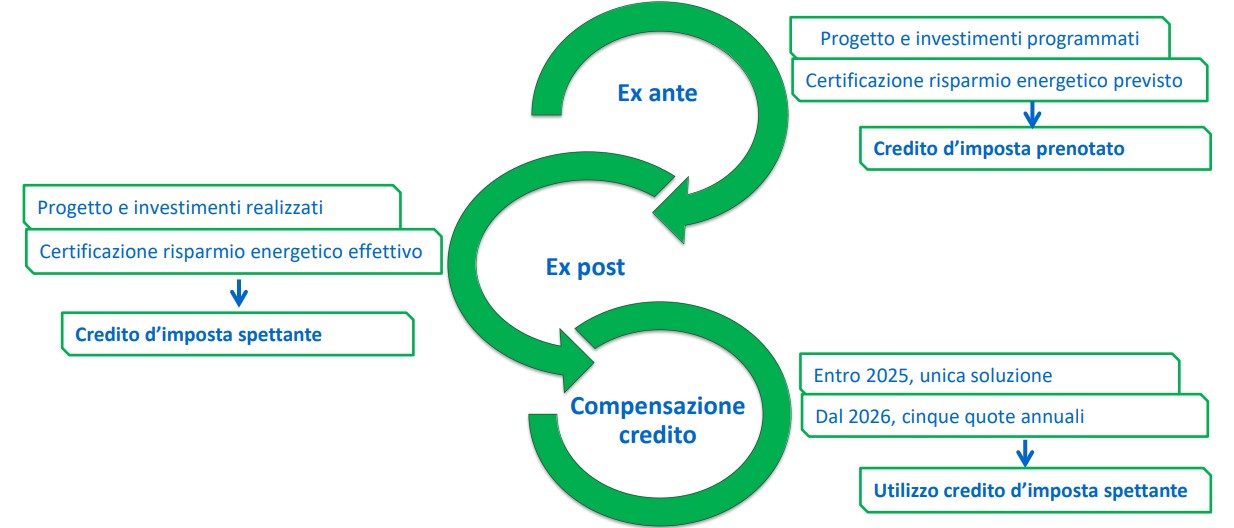
Ex Ante Certification
Companies will have to submit an initial ex ante certification to the GSE on the achievable reduction in consumption. This communication will be used to reserve the incentive in relation to the granted ceiling.
Ex Post Certification
Companies will have to submit a second ex post certification to the GSE on the actual implementation of the investments. This communication will be used to qualify for the incentive.
Tera's support
Tera is a UNI CEI 11352 certified ESCo company.
Project Identification and Definition
Description of the investment project and its cost in accordance with the regulations.
Energy saving asseveration
Verification and certification of energy consumption reduction of at least 3 percent of the production facility or, alternatively, at least 5 percent of the production processes covered by the facility.
GSE telematics practice (ex ante communication)
Drafting and submitting the application to reserve the incentive.
GSE Follow-up
Periodic communication to the GSE of the progress of the allowed investment.
Final communication to the GSE (ex post communication)
Notification of the completion of the investment to the GSE for subsequent disclosure to the Internal Revenue Service of the list of beneficiary enterprises and the amount of tax credit that can be used.
Determination of tax credit
Calculation of tax credit to be used for offsetting by December 31, 2025.
Support during GSE audits
The GSE will carry out, within the terms agreed with the Internal Revenue Service, subsequent checks aimed at verifying the technical requirements and prerequisites for the use of the benefit.
We remain waiting for the director's decree sanctioning the opening of the GSE platform and the circular containing guidelines with examples for applying the plan.
Below is the text of the Transition 5.0 Decree
For more information call + 39 055 577 297 or write to massimiliano.zattelli@teraenergy.com
Where are we
Via Riguccio Galluzzi, 22 - 50134 Florence